Who Has the Upper Hand in Today's Housing Market?Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know

Dated: May 26 2026
Views: 39
Nearly half of Veterans (49%) feel homeownership is currently out of reach, according to a recent survey from NewDay USA.
But many are closer than they think. And you might be, too.
If you’re a Veteran, you probably know the Veterans Affairs (VA) home loan benefit exists – it's been around for over 80 years. What you might not know is what it actually covers. Three misconceptions trip up Veterans the most (see graph below):
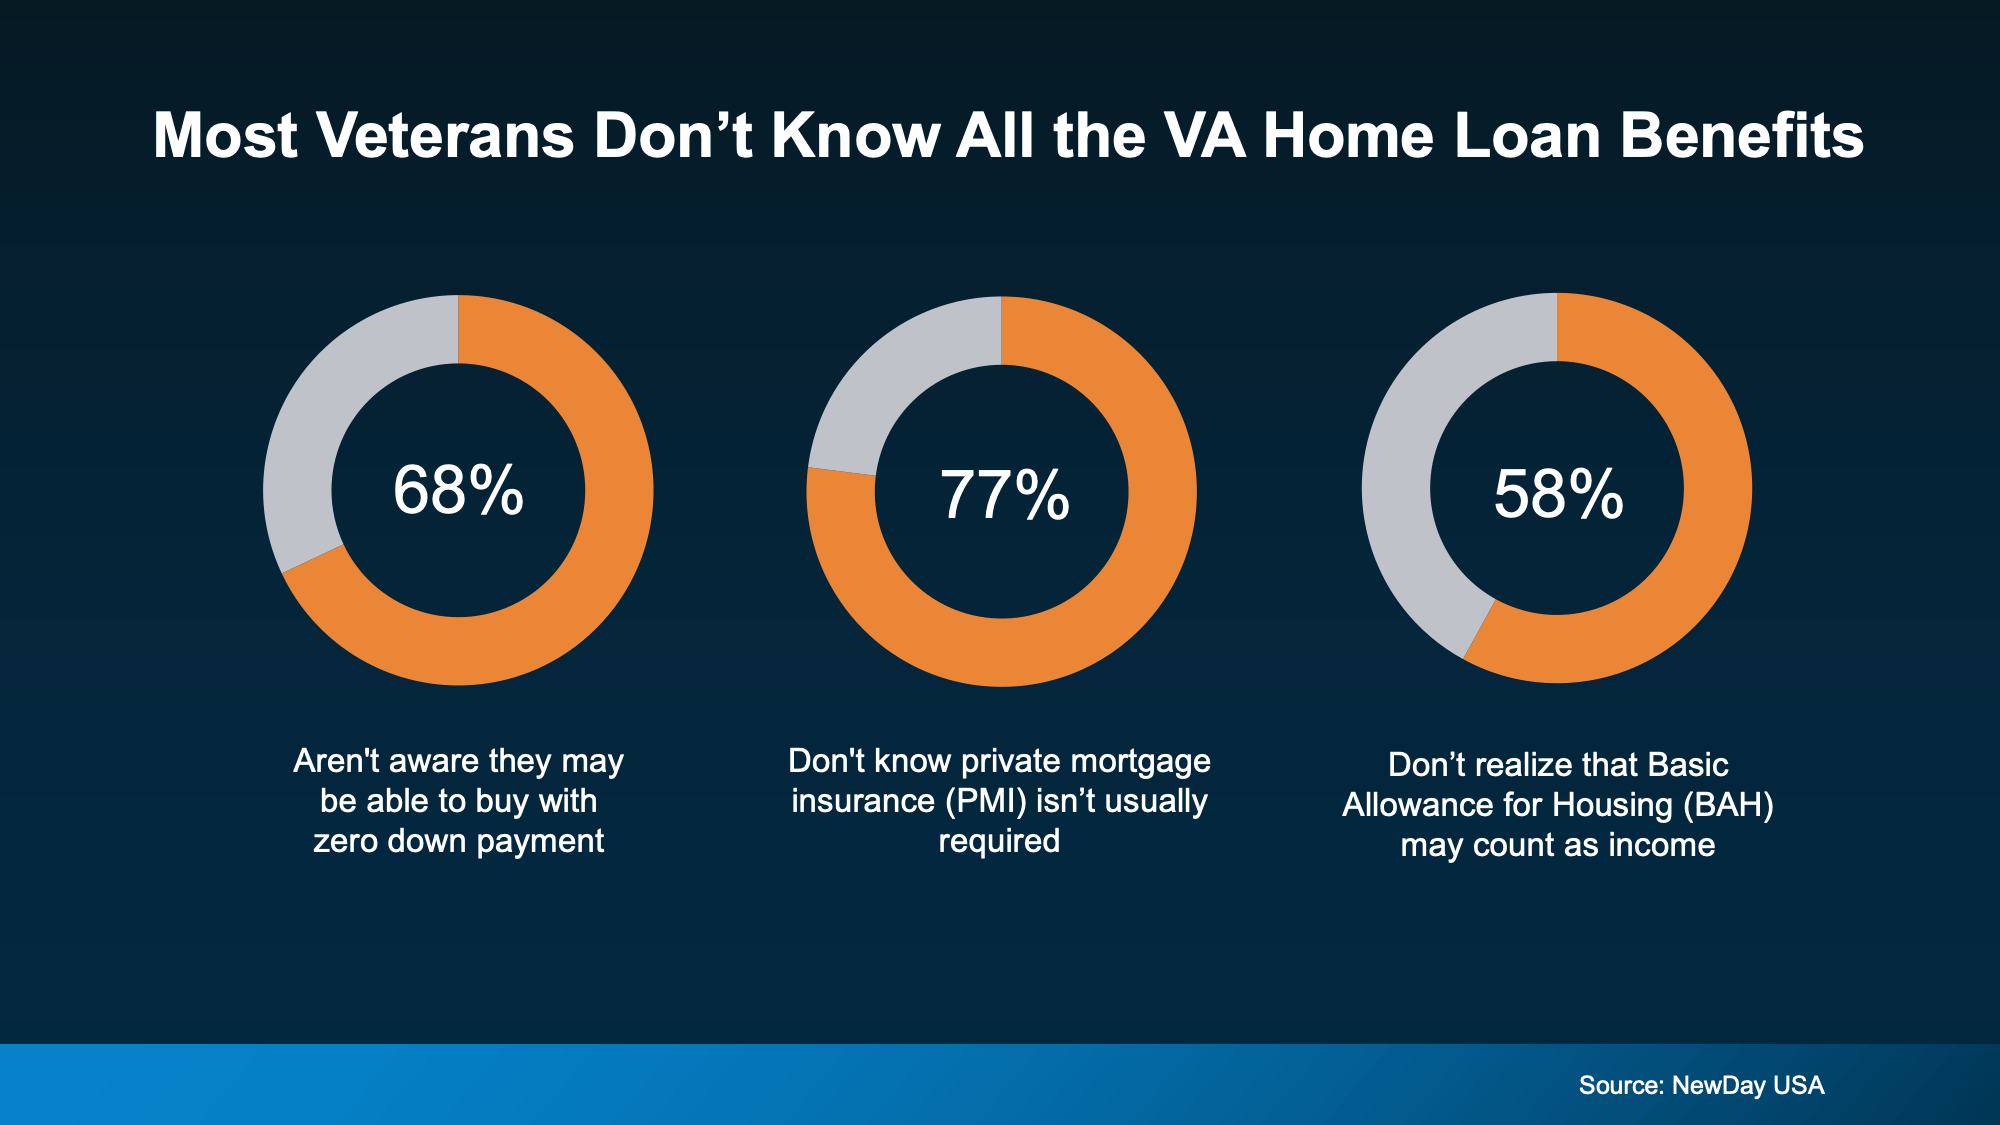 Any one of those beliefs could be holding you back. Let’s walk through all three, so you have the information you really need.
The potential to put zero money down is probably the biggest perk of a VA loan, but most homebuyers don’t even realize that’s an option. According to the NewDay USA survey, many respondents guessed they’d need to save somewhere between $10,000 and $19,900 before they could buy. That’s years of saving for an upfront cost that isn’t always required.
According to the Department of Veterans Affairs, with VA loans, there can be limits on the types of closing costs buyers have to pay. That means more money stays in your pocket on closing day – and you have less to save up for before you can buy. The benefit combined with the down payment perk can speed up your buying timeline.
Unlike many other loan options, VA loans typically don’t require private mortgage insurance (PMI), even with low or no money down. If you take out a conventional loan instead, you could pay $100 to $300 a month in PMI until you hit 20% equity, according to NewDay USA. Over time, that’s a difference of thousands of dollars.
If you’re on active duty or if you’re a qualifying reservist, your Basic Allowance for Housing (BAH) and Basic Allowance for Subsistence (BAS) may count toward income qualification on a VA loan. So, if you were running the numbers without factoring your BAH or BAS in, you could qualify for more than you thought. Both BAH and BAS are non-taxable, so they can help raise the amount you can qualify for.
VA home loans can put homeownership within reach, and a trusted lender can help make sure you understand the details before you move forward.
If you’re active duty, you’ve served, or know someone who has, connect with a trusted lender who can walk you through whether you’d qualify and what the VA benefit offers. You may be able to buy a home sooner than you thought.
Interested in more real estate tips? Feel free to contact me directly!
Providing a superior level of informed, professional real estate services to buyers and sellers throughout Central Minnesota. We have agents specializing in residential, commercial, multifamily, new construction, existing, investment properties, foreclosures/REO, and short sales with offices located in:
Multiple Office Locations To Serve YOU!
Saint Cloud 320-259-4554
Princeton 320-983-3555
Sartell 320-259-4554
Little Falls 320-259-4554
Minneapolis 763-565-2000
Hutchinson 320-455-9127
Litchfield 320-298-1140
Premier Real Estate specializes in MANY areas around Central MN including Saint Cloud, Waite Park, Rice, Royalton, Sartell,
Who Has the Upper Hand in Today's Housing Market?Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know
How to Find the Right Neighborhood When You MoveHouse hunters can focus so much on a house they want that they unintentionally slight other aspects of a new location. Your new neighborhood is at
Less House, More Home: Why Smaller Homes Are Paying Off for Today’s BuyersYou started shopping with a specific mental image of your future home in your mind. Then the houses in your budget
Do You Still Need a Home Office?Dedicated home offices are transitioning from must-haves to maybes, as many employees spend more days at the workplace. The home office isn’t disappearing, but
 The data relating to real estate for sale on this web site comes in part from the Broker Reciprocity Program of the Regional Multiple Listing Service of Minnesota, Inc. Real estate listings held by brokerage firms other than Premier Real Estate Services are marked with the Broker Reciprocity logo or the Broker Reciprocity thumbnail logo (little black
house) and detailed information about them includes the name of the listing brokers.
The broker providing these data believes them to be correct, but advises interested parties to confirm them before relying on them in a purchase decision.
© 2026 Regional Multiple Listing Service of Minnesota, Inc. All rights
reserved
By searching, you agree to the End User License Agreement.
Digital Millennium Copyright Act (DMCA) Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. 512 (the "DMCA"), provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices and counter-notices should be sent in writing by mail to Michael Bisping, Director, Customer Relations, Regional Multiple Listing Service of Minnesota, Inc, 2550 University Avenue West, Suite 259S
Saint Paul, MN 55114 or by email to mbisping@northstarmls.com. Questions can be directed by phone to 651-251-3200.
